If you’ve ever tried to apply for health insurance on HealthCare.gov or check your eligibility for financial assistance, you’ve likely stumbled across the term MAGI – short for Modified Adjusted Gross Income.
For W-2 employees with a steady paycheck, estimating income is relatively simple. But if you’re self-employed, work 1099 contracts, earn commissions, or run a side business, trying to project your MAGI for the upcoming year can feel like trying to guess the weather six months in advance.
Estimate too high, and you might miss out on lower monthly premiums or zero-dollar plans. Estimate too low, and you could owe money back to the IRS when tax season rolls around.
In this guide, we break down the simple step-by-step formula to calculate your MAGI accurately – no accounting degree required.
What is MAGI and Why Does HealthCare.gov Use It?
MAGI is the specific income calculation used by HealthCare.gov (and state agencies like Oklahoma’s SoonerCare) to figure out your eligibility for Premium Tax Credits (subsidies) and cost-sharing savings.
It’s important to understand two key things about MAGI:
- It is based on the coverage year, not last year’s taxes. If you are applying for 2026 coverage, HealthCare.gov cares about what you expect to make in 2026, not what you made on your 2024 or 2025 tax return.
- MAGI doesn’t appear as a single line on your tax return. Instead, it starts with your Adjusted Gross Income (AGI) from IRS Form 1040 (Line 11) and adds back a few specific tax-exempt items.
For roughly 95% of tax filers, MAGI is identical (or very close) to your AGI.
The 3-Step Formula to Calculate Your MAGI
To figure out your household MAGI, gather your pay stubs, bank statements, or recent tax returns, and follow these three steps:
Step 1: Start with Your Adjusted Gross Income (AGI)
Your starting point depends on how you earn your money:
- W-2 Employees: Start with your taxable wages (found on Line 1z of IRS Form 1040 or your W-2 Box 1). Note that this is after pre-tax deductions like 401(k) contributions and employer health insurance are taken out.
- Self-Employed/1099 Contractors: Start with your net business profit, not your gross revenue. Take your total projected income and subtract allowable business expenses (what you report on Schedule C).
Step 2: Add Back Tax-Exempt Incomes (The “Modified” Part)
Under ACA rules, you must add three specific types of non-taxable income back to your AGI if you receive them:
- Non-taxable Social Security Benefits: Include untaxed Social Security or SSDI payouts (do not include SSI).
- Tax-Exempt Interest: Interest earned from tax-exempt municipal bonds.
- Excluded Foreign Earned Income: Income earned working overseas that was excluded from U.S. income tax.
Step 3: Subtract Allowed Pre-Tax Deductions
Certain deductions lower your MAGI, which can help you qualify for better subsidies. Make sure to subtract:
- Contributions to a Traditional IRA (not a Roth IRA).
- Contributions to a Health Savings Account (HSA).
- Student loan interest you paid.
- Self-employed health insurance premiums.
What Counts (and What Doesn’t) – Cheat Sheet
| What to INCLUDE in MAGI | What to DEDUCT (Lowers MAGI) | What to EXCLUDE Completely |
|---|---|---|
| W-2 Wages, Tips & Bonuses | Traditional IRA Contributions | Supplemental Security Income (SSI) |
| Net 1099 / Self-Employment Profit | HSA Contributions | Child Support Received |
| Unemployment Benefits | Student Loan Interest Paid | Gifts & Inheritance |
| Pensions & 401(k) Withdrawls | Pre-tax 401(k) Salary Deductions | Roth IRA Withdrawls |
| Rental Property Net Income | Self-Employed Health Premiums | Life Insurance Payouts |
How to Estimate Income When Your Earnings Fluctuate
If you run a business, work on commission, or pick up seasonal gigs, your monthly income isn’t static. Here are two practical ways to build a realistic estimate:
Method 1: The Year-to-Date (YTD) Average
If your earnings are relatively steady throughout the year, use this quick math formula:
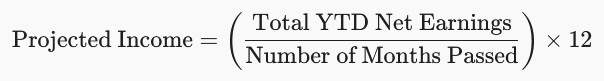
Example: if you’ve earned $15,000 net over the first 5 months of the year:
($15,000/5) x 12 = $36,000 projected annual MAGI.
Method 2: Seasonal Adjustments
If you work in an industry with dramatic seasonal swings, don’t rely on simple YTD averages. Instead:
- Look at your previous year’s Schedule C as a baseline
- Adjust for any expected growth or slowdowns in the upcoming year
- Calculate high-volume months and low-volume months separately to arrive at arrive at a realistic annual total.
What Happens If Your Income Estimate Is Off?
HealthCare.gov understands that income estimates aren’t set in stone. However,it’s important to manage your application throughout the year:
- If you end up making MORE than estimated: You may have received more subsidy assistance than you were eligible for. The IRS will adjust this when you file Form 8962 at tax time, and you may have to pay back a portion of the tax credit.
- If you end up making LESS than estimated: You paid more for health coverage than you needed to! The IRS will refund the difference to you as a tax credit when you file your tax return.
Keep in mind, you can log into your HealthCare.gov account and update your estimated income at any time during the year. If you land a large contract or experience a sudden dip in revenue, updating your account immediately ensures your monthly premium subsidy adjusts right away.
FAQs
Q: Does child support count toward my MAGI?
No, Child support payments received are not taxable income, and do not count toward your MAGI.
Q: Does my spouse’s income count if we file taxes jointly?
Yes. MAGI includes the total combined income of everyone included on your federal tax return.
Q: What if my income drops below the minimum limit for Marketplace subsidies?
If your household MAGI falls below 100% of the Federal Poverty Level (or below 138% FPL in Oklahoma). HealthCare.gov will automatically screen you for Oklahoma SoonerCare (Medicaid) eligibility.
Want an Expert to Double-Check Your Numbers?
Calculating MAGI and navigating Marketplace tiers doesn’t have to be a solo effort.
Whether you’re self-employed, changing jobs, or simply trying to get the lowest possible monthly premium, our local team is here to help. Drop by our office or give us a call for a free, zero-pressure income review. We’ll help you estimate your MAGI accurately, check your doctor networks, and find the right coverage for your household budget.